As the number of vehicles grows, how insurance policies are priced becomes more important for businesses and vehicle owners alike. One topic that has drawn particular attention recently for individuals who own several vehicles is the tariff rule based on a 5-vehicle threshold.
This rule revisits the relationship between a vehicle being registered to a private individual and it being treated as personal use for insurance purposes.
So what exactly does the 5-vehicle limit mean? How does policy pricing change as the number of vehicles registered to one person grows? And what are the financial and operational consequences for businesses that run fleets?
Why Does the 5-Vehicle Limit Matter?
When motor insurance is priced, insurers may consider not only a vehicle’s make, model or use, but also the profile of the policyholder and of the vehicle park as a whole.
In the past, individuals with several vehicles could register them in their own name and benefit from the tariffs applied to personal users. For businesses with small and medium-sized vehicle parks in particular, this offered an alternative structure.
The new practice, however, introduces a threshold for the number of vehicles registered to an individual.
The First 5 Vehicles Fall Under the Personal Tariff
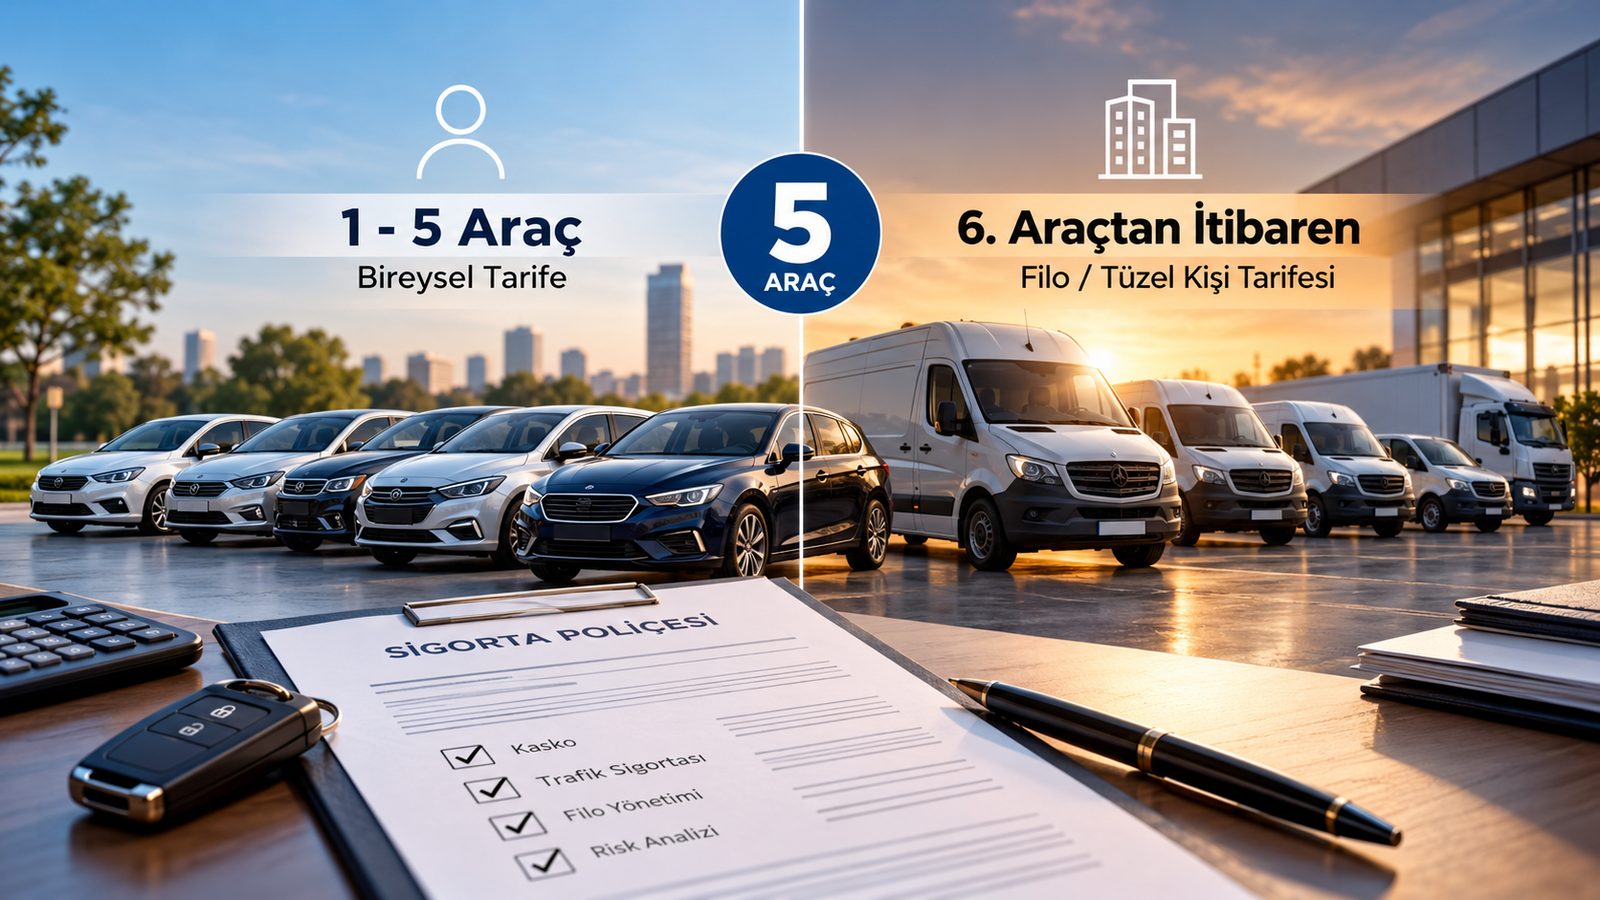
For vehicles in the same group registered to an individual, the first 5 vehicles can be assessed under the private/personal use tariff, provided they meet the relevant conditions.
For individual owners with only a few vehicles, therefore, the rule does not turn their cover into a fleet tariff.
A Different Assessment from the 6th Vehicle
Once the number of vehicles exceeds 5, however, things change significantly.
When the number of vehicles registered to an individual reaches 6, the 6th and any subsequent vehicles can be assessed under the fleet/corporate tariff — even though the registered owner is still a private individual.
In other words, having a person’s name on the registration document does not, on its own, guarantee that a vehicle stays under the personal tariff for insurance purposes.
How Does This Affect Fleet Owners?
The 5-vehicle threshold matters especially for businesses that run several vehicles in distribution, field sales, technical service, logistics, rental and similar operations.
As the number of vehicles grows, calculating insurance costs means looking not just at each vehicle’s features, but at the fleet as a whole and its risk profile.
Registering Vehicles to Individuals May Not Pay Off
In the past, some businesses chose to register vehicles used for company operations to individuals such as partners or the business owner. One of the main reasons was the expectation that personal insurance tariffs would be more favourable.
Once the 5-vehicle threshold is exceeded, however, this approach may not deliver the expected premium advantage.
The decision to register vehicles to a company or to an individual should therefore not be based on the insurance premium alone; tax, accounting, legal liability, intended use and operational needs should all be weighed together.
Fleet Budgets Need Recalculating
Businesses with more than 5 vehicles need to plan their insurance budget more carefully.
Especially at motor own-damage (kasko) and compulsory motor liability renewals, it is important not to assess last period’s premiums and new quotes on the same assumptions.
Fleet size, how the vehicles are used, claims history, vehicle group and the insurer’s pricing criteria can all affect the total cost.
When preparing the annual budget, rather than looking only at current premiums, vehicles planned to join the fleet in the coming period should also be taken into account.
What Should Businesses Near the 5-Vehicle Limit Watch For?
For businesses with 4–5 vehicles, the issue is even more important. Buying a new vehicle or adding an existing one to the fleet may bring a different tariff assessment for insurance purposes.
It is therefore useful for businesses to keep regular track of the following:
- The total number of vehicles registered to individuals or legal entities
- The purpose and type of use of each vehicle
- Policy renewal dates
- Kasko and motor liability claims history
- Whether vehicles are assessed in the same or different groups
- The impact of new vehicle purchases on insurance costs
- Alternative quotes available under a fleet tariff
Factoring in the insurance cost before buying a new vehicle can prevent budget gaps from appearing later.
Don’t Look Only at the Registration When Deciding
Who a vehicle is registered to matters, but it is not the only factor in insurance pricing. Besides the number of vehicles, the type of use, risk profile, policy history and the tariff criteria applied by insurers may all be taken into account.
The general assumption that “if we register the vehicle to an individual, we’ll get the personal tariff” may therefore fall short, especially where there are more than 5 vehicles.
Planning Ahead with Your Insurance Agent Matters More
For growing fleets, it is healthier to address insurance planning as early as possible, rather than after vehicles have been bought or renewal dates have arrived.
For example, if a business currently has 5 vehicles and plans to buy 2 more in the coming period, calculating insurance costs under different scenarios before the purchase can give a more accurate picture of its total cost of vehicle ownership.
The role of an experienced insurance agent here should be not just to issue policies, but to carry out a risk and cost analysis suited to the business’s vehicle park.
Conclusion: The More Vehicles, the More Planning Matters
The 5-vehicle threshold is becoming a criterion to keep in mind, especially for individuals with several vehicles and for small and medium-sized fleets.
The different tariff approach that may apply to the first 5 vehicles and to the 6th vehicle onwards requires owners to look not only at how vehicles are registered, but at the whole vehicle park and its insurance costs together.
For businesses with a growing number of vehicles, the right approach is therefore to plan vehicle registration, insurance tariff, renewal dates and total fleet cost together.
Before buying new vehicles or expanding a fleet, it is also important to confirm the current practice with the insurer and an authorised agent, as policy conditions and pricing criteria may vary by insurer, vehicle group and current regulations.
 Ayşe İsmihan AslanRead more
 Ozan Aslan